01
Advisory and disputes are mixed
Tax planning, audit objections and representation in a dispute are different activities. A useful service page identifies their scope, documents and the provider's actual role.
Businesses seek tax advisers for specific disputes, audits and transactions. I examine which firms AI recommends for those needs, which claims can be verified and where the practice is absent from relevant answers.
A generic promise to solve tax problems does not answer questions about a particular tax, procedure or business situation. The supporting information changes with the service.
Tax planning, audit objections and representation in a dispute are different activities. A useful service page identifies their scope, documents and the provider's actual role.
Claims about successful appeals or cancelled assessments need traceable evidence and permission to publish. One decision does not guarantee the same outcome for another taxpayer.
Prospects need to know what an initial consultation covers, how complaints are considered and what evidence to prepare. Descriptions should follow current tax-authority procedures.
Sample commercial prompts for baseline measurement. The final matrix reflects the actual practice, jurisdiction and tax types.
| Prospect's question | Evidence needed | GEO action |
|---|---|---|
| Who can help after a corporate tax audit decision? | Audit and appeal scope, roles, documents, procedural steps and experience | Publish a verifiable process and distinguish phases of representation |
| Which adviser handles corporate VAT deductions? | Actual service scope, specialist qualifications, examples and engagement terms | Prepare a focused practice profile and factual FAQ |
| Who represents businesses in profit-tax assessment disputes? | Subject-matter experience, publishable decisions and professional role | Connect services to documented analysis without outcome guarantees |
| Who conducts tax due diligence before an acquisition? | Review scope, document categories, confidentiality and deliverables | Describe this as a separate business decision and service |
I check actual services, professional roles, accessible publications and authorised examples. Regulatory descriptions are checked against tax-authority primary sources.
GAEO's existing law-firm methodology provides a starting point. No completed GEO success story for a tax-law practice is claimed here.
Start with buyer questions and baseline visibility, then develop accurate service evidence and remeasure the same prompts.
Separate advisory, disputes, audits and transaction due diligence. Record baseline AI answers for stable non-brand query groups.
Review practice credentials, permitted disclosures, source documents and procedural accuracy.
Prepare a structured brief for focused services, profiles, procedural FAQs and sourced expert articles.
Check the same AI services and prompts, separately recording mentions, correct roles and supporting citations.
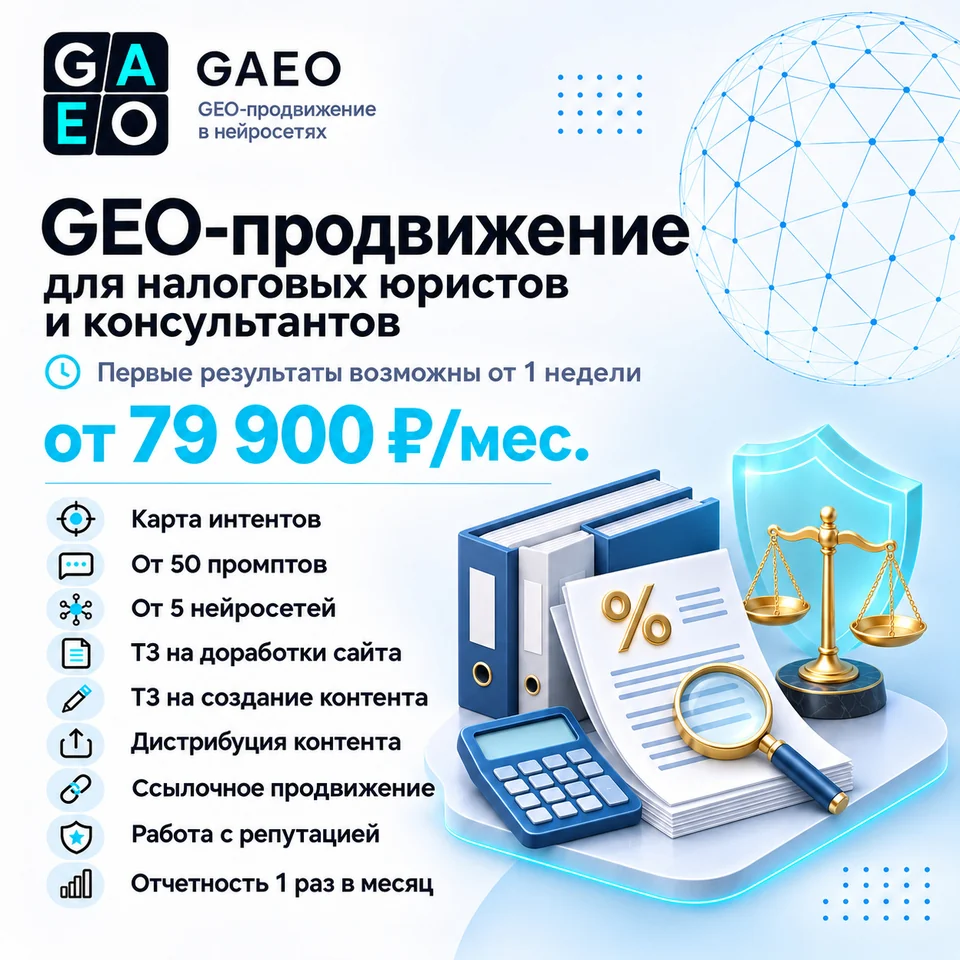
Three published monthly plans use the same GAEO prices across sectors. Final scope follows the baseline and project requirements.
I lead the strategy; your team implements website and content specifications.
I study your product, create the content and organize publication.
Contractual BMR targets: baseline +5 / +10 / +15 percentage points in months 1 / 2 / 3.
Start with a free mini-audit or a full GEO audit. A monthly plan includes 50 prompts and 5 AI platforms; broader scope is calculated separately.
No. GEO work seeks better discovery and factual representation in AI answers. Tax appeal outcomes depend on evidence and decisions by authorities or courts.
No. Use permitted anonymised examples and public decisions. Taxpayer and professional confidentiality must be respected.
Describe the actual work: advice, compliance, audit response, tax appeals or representation. Do not attribute services or credentials that the provider does not possess.
Fix a consistent set of prompts by tax type, business issue and geography, the tested AI services and the baseline BMR before comparing later results.
GAEO's standard audit and monthly plans apply. Scope depends on jurisdictions, service areas, query volumes and source coverage.
Independent GEO/AEO specialist with business experience since 2008. I personally carry out the diagnostic and build an industry-specific plan, separating verified sources from assumptions.
Professional biography ↗Share the practice website, actual tax services, jurisdictions and verifiable public materials to discuss a focused initial audit.
Discuss an initial audit