01
Different engagements are bundled together
Financial statement audits, agreed-upon procedures, tax advice and management consulting have different objectives and deliverables. A generic menu creates unsuitable matches.
A finance director needs an audit firm matched to the reporting engagement, industry and eligibility requirements. I examine which firms AI recommends, whether the evidence is verifiable and whether the answers confuse independent audit with bookkeeping or general consulting.
A company name alone cannot establish eligibility, industry skills or scope. A useful AI shortlist has to connect an actual buyer request to substantiated services.
Financial statement audits, agreed-upon procedures, tax advice and management consulting have different objectives and deliverables. A generic menu creates unsuitable matches.
A company website is not proof of an up-to-date professional register entry. Public-interest entity engagements may require separate checks against the special register.
Brand names without permissions, engagement details or dates do not establish sector capability. Client confidentiality and auditor independence limit public disclosures.
These are proposed commercial prompts for a baseline study, not observed recommendation results or a ranking of named firms.
| Buyer question | Evidence required | GEO action |
|---|---|---|
| Which firm should audit the financial statements of a manufacturer? | Applicable audit obligation, register status, relevant industries and engagement scope | Publish verifiable specialisms and actual service boundaries |
| Who can audit a Russian public-interest entity? | Applicable requirements and the firm's current entry in the Federal Treasury special register | Separate standard engagements from special eligibility requirements |
| Who can perform a voluntary audit ahead of an investment deal? | Purpose, reporting scope, intended deliverable, independence and team | Describe voluntary engagements and limits in precise terms |
| What separates an audit from tax advice and bookkeeping? | Contract scope, expected output, qualifications and service compatibility | Give each service its own buyer intent and supporting evidence |
Federal Law 307-FZ defines audit activity and the register of auditors and audit organisations. The self-regulatory organisation maintains the general register, while the Federal Treasury publishes a special register for firms auditing public-interest entities. A specific firm's status still requires a current verification.
This is an evidence-led GEO method, not a completed GAEO audit-sector client case. General management consulting has its own catalogue entry #72, with a different set of buyer requirements.
The work starts by identifying the engagements the firm actually offers. I then verify eligibility, improve its accessible evidence and measure recommendation accuracy again.
Split non-branded prompts by statutory audit, voluntary engagement, sector and client type. Keep the exact initial set for repeat measurements.
Review professional registers, service descriptions, specialists and whether past work can lawfully be disclosed.
Prepare briefs for engagement pages, sector methodology, professional profiles and useful publications based on primary sources.
Re-run the buyer questions and check whether AI correctly represents the firm's actual status, qualifications and scope.
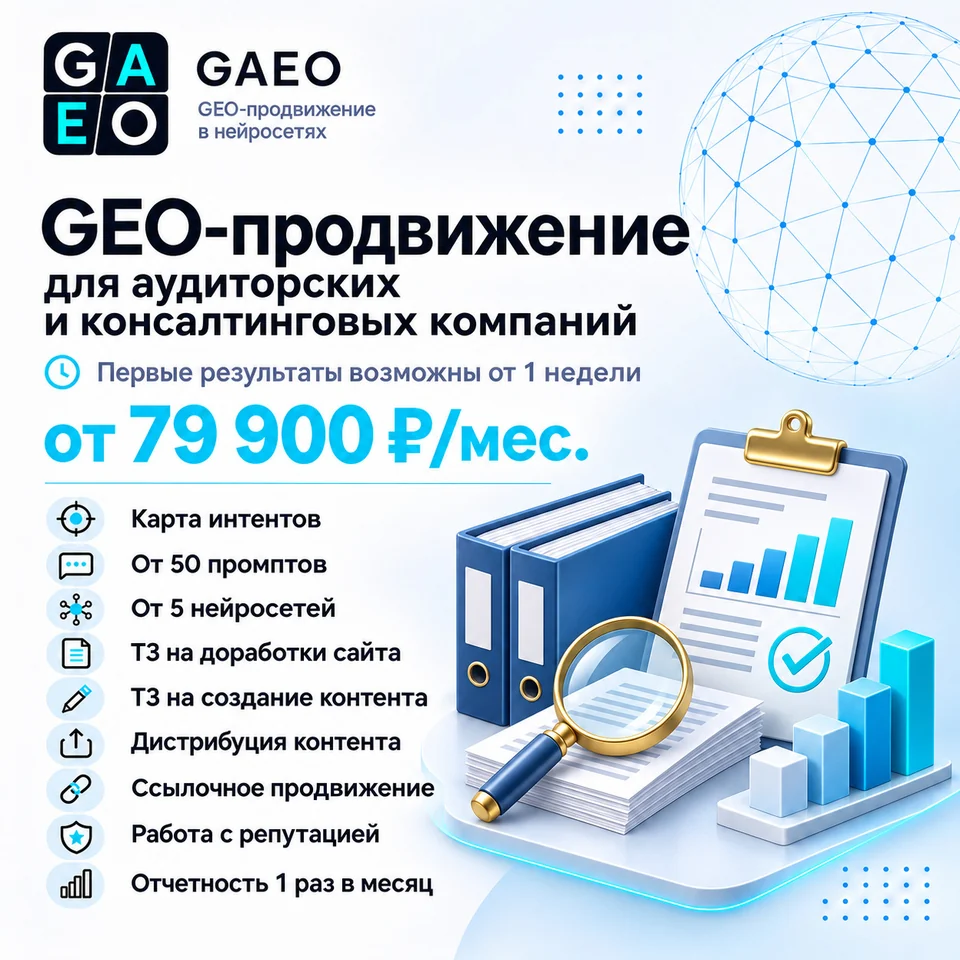
Three published monthly plans use the same GAEO prices across sectors. Final scope follows the baseline and project requirements.
I lead the strategy; your team implements website and content specifications.
I study your product, create the content and organize publication.
Contractual BMR targets: baseline +5 / +10 / +15 percentage points in months 1 / 2 / 3.
Start with a free mini-audit or a full GEO audit. A monthly plan includes 50 prompts and 5 AI platforms; broader scope is calculated separately.
Yes, when the firm genuinely offers both. They involve different deliverables, eligibility checks and buyer intent, and deserve distinct descriptions.
No. Verify the current entry in the applicable register. Public-interest entity engagements may also require checking the Federal Treasury's special register.
Only where permissions, confidentiality and independence allow it. Otherwise explain the method without identifying clients or inventing outcomes.
No. It measures the share of AI recommendations within an agreed prompt sample. Leads and signed contracts are separate outcomes.
GAEO's published plans apply. The actual scope depends on the firm's service lines, target clients and baseline query matrix.
Independent GEO/AEO specialist with business experience since 2008. I personally carry out the diagnostic and build an industry-specific plan, separating verified sources from assumptions.
Professional biography ↗Share your website, real engagement types and register references. I will propose a suitable initial prompt set.
Discuss an initial audit